Acorns: Save & Invest Money

Screenshots
Details
- Rating
- 77.82K reviews
- Version
- 4.207.0
- Developer
- Acorns
Analysis by Norviv
I tried Acorns as a household money tool rather than treating it like a simple investing shortcut. That distinction matters. The app is built around a smart investing plan for stocks and ETFs, but its real appeal is how quietly it can fit into an established routine. One person can use it to make regular investing feel less demanding, while another household member can remain focused on bills, savings, or day-to-day spending.
That convenience is also where I found the main question: who is actually managing the account, and who is merely helping with the routine? On a shared phone or tablet, those boundaries need to be clear. Acorns is a finance app from Acorns, available free of charge, with an Everyone content rating. It has been around since October 7, 2014, and its current version is 4.207.0 for devices running operating system version 10 or later.
My overall impression is positive for someone who wants a low-friction way to begin investing in stocks and exchange-traded funds. I would not present it as a replacement for a full brokerage account, a detailed budgeting system, or a serious retirement-planning service. It works best when its automation reduces hesitation without making the user forget that invested money can rise and fall.
How Acorns fits into a shared household routine
I find a shared household routine works best when it gives both people clarity without turning account access into a free-for-all. Agree on a regular moment to check whether investing still fits the budget, and keep the account owner responsible for any changes. That simple division makes it easier to talk about the next question: how to keep the routine useful when household needs shift.
A realistic shared-device scenario
Imagine a couple sharing a tablet at home. One person handles the weekly household review and opens Acorns after checking the bank balance. The other person wants to invest but does not want to study individual companies or decide what to buy every few days. In that situation, the app can serve as a personal investing routine inside a wider household system.
The useful arrangement is not to pass the device around casually. Instead, the account owner should open the app, review the information, and make the decisions. A partner can help with the household conversation—whether the money is genuinely available, whether an upcoming bill changes the plan, and whether the investment approach still matches the family’s comfort level—but the account itself should remain clearly associated with its owner.
This sounds obvious, yet it is an important practical distinction. A shared device can make an app feel communal even when the financial responsibility is individual. I would avoid leaving the account open on a family tablet, especially if children use that device for games or schoolwork. A quick glance at a balance or an accidental tap is not the same thing as informed participation in an investment decision.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
Acorns is particularly comfortable in a household where one person wants to take the first step and the other wants visibility rather than control. The app can become part of a monthly money check-in: look at the available cash, review the investment plan, discuss upcoming expenses, and leave the account alone if the household budget is tight. That is a healthier use than opening it repeatedly to react to every market movement.
What setup should establish before anyone invests
When I set up a finance app for shared use, I start with boundaries rather than features. The account owner should decide which email address, phone number, and payment details belong to the account, then keep those details separate from a partner’s unrelated financial information. A shared device does not need to mean shared credentials.
I also recommend agreeing on the purpose of the account before making the first investment. Is it intended for long-term growth, a future purchase, or simply learning how market-based investing feels? The answer affects how comfortable you should be with fluctuations and how often you should review the plan. Acorns can make investing feel approachable, but it cannot decide whether the money is truly available for that purpose.
One of the most useful habits is to check the funding source before enabling or continuing any recurring behavior. A small contribution may feel harmless, but several small withdrawals can become inconvenient when rent, school costs, travel, or an irregular bill arrives. I would keep a separate buffer in the household budget and treat investing as money that can remain committed through market changes.
Another practical tip is to use a private device or a separate user profile whenever possible. If that is not realistic, close the session after use and avoid saving financial details where other household members can reach them. Acorns is not a household dashboard, so trying to make it function like one can create confusion about ownership and access.
Coordinating decisions without turning investing into a daily debate
Shared finances often fail because every person uses a different review schedule. One partner checks the account every morning, another only looks at the household budget once a month, and both interpret the difference as a problem. I found that Acorns works more calmly when the household agrees on a simple review rhythm.
A monthly conversation is usually more useful than constant monitoring. Discuss whether contributions still fit the budget, whether the original goal has changed, and whether the selected investing approach remains understandable. If the market has moved sharply, the right response is not automatically to change course. First ask whether the household’s time horizon or ability to tolerate risk has actually changed.
This is one of the app’s less obvious trade-offs. Its simplicity can help a hesitant beginner start, but simplicity can also hide the amount of responsibility that remains with the user. The app may organize the experience, yet the user still needs to understand what is being funded, why the plan was chosen, and what could happen when markets decline.
I would also separate coordination from permission. A partner may reasonably expect to know that household money is being invested, especially if the contributions affect shared cash flow. That does not mean every person using the same device should be able to make changes. Clear agreement about whose money is involved prevents a convenient routine from becoming a source of resentment.
Age, trust, and the meaning of an Everyone rating
The Everyone rating makes Acorns approachable from an app-store perspective, but I would not interpret that as a recommendation for unsupervised investing by a child. Finance requires context that an age label cannot provide. A young person may understand that an account shows money going up and down without understanding market risk, access rules, tax consequences, or the difference between investing and saving.
For a household with teenagers, I would use the app as a conversation starter rather than hand over responsibility without guidance. Show how a plan is reviewed, explain that an investment balance is not the same as cash in a checking account, and discuss why a short-term expense should not depend on market performance. The adult who owns the account should remain accountable for the decisions.
Trust matters just as much between adults. If a partner is helping with the app, agree on what that help means. It might mean reviewing a plan together, checking whether a contribution still fits the budget, or discussing a longer-term goal. It should not mean casually sharing passwords or assuming that access to a shared device equals authorization to change financial settings.
For older relatives or a less confident smartphone user, Acorns may be easier to understand than a platform filled with charts, order types, and lists of individual securities. Even then, I would sit beside the person during setup and make sure they can explain the basic arrangement in their own words. A clean interface is helpful, but it should not replace informed consent.
Where the app is stronger than usual alternatives
Compared with choosing individual stocks through a traditional brokerage, Acorns offers a less intimidating starting point. The user can focus on a plan built around stocks and ETFs rather than researching every company. That is valuable for someone who would otherwise leave money idle because the choices feel overwhelming.
Compared with a basic savings account, the app introduces market exposure, which creates the possibility of growth but also the possibility of loss. I would not use it for money needed soon or for an emergency reserve. A savings account is usually the clearer home for cash that must remain stable and available. Acorns makes more sense for money that can stay invested through normal market movement.
Compared with a full-service brokerage, the experience is more guided and less flexible. An experienced investor who wants precise control over securities, orders, portfolio construction, or tax strategy may find the guided approach restrictive. In that case, a conventional brokerage or a professional adviser could be a better fit, depending on the person’s needs.
Compared with a budgeting app, Acorns is not primarily about categorizing every purchase or planning each bill. It can sit alongside a budget, but it should not be expected to replace one. My preferred workflow is to budget first, confirm the available amount, and then treat investing as a deliberate follow-through rather than as a substitute for knowing where the money goes.
Small workflows that make the experience more useful
My first practical workflow is the “budget before app” check. Before opening Acorns, I look at the household’s upcoming obligations and available cash. If the month is unusually expensive, I pause the investing conversation rather than assuming a small recurring amount will not matter. That simple order of operations keeps the app from becoming an automatic claim on money needed elsewhere.
The second is a written purpose statement. I would note, in plain language, what the account is for and what it is not for. For example, it might be intended for a long-term goal and not for next month’s utilities. This is especially useful on a shared device because both adults can understand the role of the account without needing to inspect it constantly.
The third is a “do not react immediately” rule. If the balance changes, wait until the planned review time unless there is a genuine household cash-flow issue. That rule prevents the app’s convenience from turning into emotional market timing. It also gives a partner or family member room to ask sensible questions before anyone changes the plan.
A fourth useful habit is to review the account after a life change, not merely after a market change. A new job, reduced income, relocation, major debt, or a new near-term goal can matter more than a temporary price movement. Acorns is easiest to use responsibly when the household updates the plan because circumstances changed, not because the screen looked uncomfortable for a day.
Who should choose Acorns, and who should skip it
I think Acorns is a strong match for a beginner who wants a guided path into investing and prefers stocks and ETFs to remain in the background. It is also suitable for a busy household where one person wants a repeatable routine instead of a research project. The free entry point lowers the barrier to trying the app, although users should still pay attention to the terms and any account-related costs that may apply in their situation.
It is less suitable for someone who needs a detailed spending plan, wants to trade actively, or expects complete control over every investment choice. It is also a poor choice for money that must be protected from market fluctuations or accessed on a short timetable. The app’s friendly presentation should not be mistaken for a guarantee or for a replacement for financial judgment.
I would also hesitate to recommend it to a household that cannot agree on ownership and funding. If partners are already unclear about which money is shared, which money is personal, and who can approve changes, adding an investment app may intensify the problem. Resolve those boundaries first; the app cannot do that coordination for you.
Performance, reach, and everyday confidence
The scale of the service suggests that it has reached far beyond a niche audience. Acorns holds a 4.7 average from around 407 thousand ratings, has around 78 thousand written reviews, and has passed 10 million installs. Those figures do not decide whether it belongs in your household, but they do indicate that the app is familiar to a large number of mobile users.
I found that broad reach reassuring in one limited sense: the product is designed for people who may not already feel at home in investing software. Still, popularity cannot tell you whether its approach is suitable for your goals. A highly rated guided experience can remain the wrong tool for a person who needs advanced control or who should be keeping the money in cash.
The technical requirements are straightforward for compatible devices, with the app supporting operating system version 10 and later. I would still keep the phone’s operating system updated and avoid using an old shared device that no longer receives security updates. Financial convenience is not worth weakening the basic security of the household’s devices.
My household verdict
After using Acorns with a shared-household perspective, I see it as a gentle entry point rather than a complete financial command center. Its best quality is the way it can turn investing from an intimidating research task into a defined routine around stocks and ETFs. That can help a beginner move from intention to action, provided the household has already handled budgeting, ownership, and access.
The app is most convincing when one person owns the account, both adults understand the purpose, and contributions come only after essential expenses are covered. On a shared device, privacy and account boundaries deserve as much attention as the investment plan itself. I would keep the session private, discuss decisions openly, and avoid treating an Everyone rating as permission for a child to manage investments alone.
My recommendation is therefore specific: choose Acorns if you want guided investing, value a simple mobile routine, and can leave the money invested for the longer term. Choose a savings tool if stability and immediate access matter more. Choose a traditional brokerage if you need detailed control. For the right household, Acorns is a practical first step; for the wrong one, its simplicity may conceal decisions that deserve more careful planning.
Frequently Asked Questions
01What is Acorns: Save & Invest Money, and how does it work?
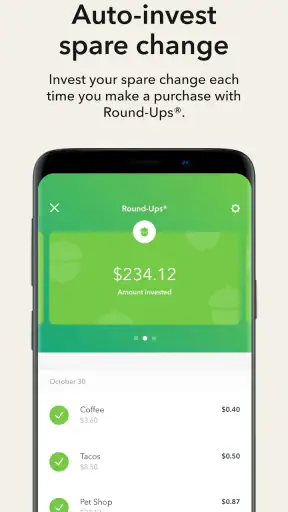
Acorns is a personal finance and investing app designed to help users save and invest with minimal effort. It can automatically invest spare change from linked card purchases, schedule recurring deposits, and provide access to diversified investment portfolios. The app also includes features such as retirement accounts, banking tools, and educational content, depending on your plan and eligibility.
02Is Acorns suitable for beginners who have never invested before?
Yes, Acorns is primarily designed with beginners in mind. During setup, the app asks about your financial goals, time horizon, and comfort with risk, then suggests a diversified portfolio. Its automated approach removes much of the complexity associated with choosing individual investments. However, users should still understand that all investments carry risk and returns are never guaranteed.
03How much does Acorns cost, and are there any additional fees?
Acorns uses subscription-based pricing rather than relying only on trading commissions. The exact monthly cost and included features can vary by plan and may change over time, so it is important to check the current pricing shown in the app or on its official website. You should also review disclosures for fund expenses, account-related charges, and any applicable third-party fees.
04Can I withdraw my money from Acorns whenever I want?
Money held in an Acorns investment account can generally be withdrawn by submitting a request through the app, although processing may take several business days. The value of your investments can fluctuate, so you may receive less than you deposited if markets have declined. Retirement accounts may have additional tax rules, restrictions, or penalties for certain withdrawals.
05Is Acorns safe to use, and what should I know about account protection?
Acorns uses security measures such as encrypted data transmission, account authentication, and identity verification to help protect user information. Investment accounts are generally subject to applicable securities regulations and may have SIPC protection within legal limits, while banking features can have separate coverage terms. Protection does not eliminate investment losses, so review the current disclosures before depositing money.


